
call us 24/7 1-800-738-WE-WIN
call us 24/7 1-800-738-WE-WIN
Serving All of Georgia, Florida, & Texas
How to Prove Aggravation of a Pre-Existing Condition
Table of Contents
- Step 1: Understand What Aggravation of a Pre-Existing Condition Means
- Step 2: Gather Aggravation of Pre-Existing Injury Evidence
- Step 3: Use Before and After Accident Medical Records to Show the Change
- Step 4: Get a Doctor Statement for Your Injury Claim
- Step 5: Establish Causation and Prepare for Insurer Review
- How Aggravation Affects a Pre-Existing Condition Personal Injury Settlement
- Conclusion: Protect Your Claim With Prompt Action
- Frequently Asked Questions
Last Updated: October 15, 2026
Step 1: Understand What Aggravation of a Pre-Existing Condition Means
Call the Merritt & Merritt Law Firm today at 404-975-1775. Offices in Atlanta, Savannah, Statesboro, and Houston.
Aggravation of a pre-existing condition means an accident or injury made a condition you already had worse. The underlying problem existed before, but the event increased your symptoms, pain, or limitations beyond your normal baseline. (Source: National Highway Traffic Safety Administration (NHTSA) data)
This is different from a new injury. A new injury creates a condition that did not exist before the accident. An aggravation makes an existing condition more severe.
Insurance companies often push back on these claims. They argue your pain was already there. That is why knowing how to prove aggravation of a pre-existing condition matters from day one.
At Merritt & Merritt Law Firm, we have spent over 45 years helping injury victims in Georgia and nationwide build strong claims, even when a prior condition complicates the picture.
Aggravation vs. a New Injury
The distinction matters for your claim. Aggravation is a worsening of symptoms from a condition you already had. A new injury is damage that did not exist before the event.
Consider a bad back from years of desk work. Then a rear-end collision leaves you unable to stand for more than ten minutes. That is an aggravation.
Now imagine the same crash causes a herniated disc in a spine that never hurt before. That is a new injury.
Both are compensable. But they require different evidence. For aggravation, you must show what your condition looked like before the accident, not just after.
Step 2: Gather Aggravation of Pre-Existing Injury Evidence
The evidence for an aggravation claim falls into a few clear buckets. Collect all of it as early as you can.
- Prior medical records: notes, imaging, and treatments for the condition before the accident
- Current medical records: new exams, imaging, and treatment notes after the event
- Symptom diaries: daily notes on pain level, function, and sleep
- Witness statements: family, coworkers, or friends who saw the change
- Work records: missed days, reduced hours, or light-duty restrictions
- Pharmacy records: prescriptions filled before and after
The goal is simple. You want a record that shows your condition was stable, then got worse.
Building a Timeline of Your Evidence
A timeline turns scattered records into a clear story. Organize everything by date, from oldest to newest.
Phase | What to Collect | Why It Matters |
|---|---|---|
Before the accident | Prior doctor visits, imaging, prescriptions | Establishes your baseline |
Day of the accident | Police report, photos, ER records | Links the event to the change |
Weeks after | Follow-up visits, imaging, therapy notes | Shows the worsening |
Ongoing | Pain diary, work limits, witness notes | Proves lasting impact |
A common mistake is waiting to organize records until the insurer asks. By then, gaps are harder to fill. Start the timeline now.
Step 3: Use Before and After Accident Medical Records to Show the Change
Before and after accident medical records are the backbone of an aggravation claim. They let a doctor compare your old baseline to your new condition.
Your pre-accident records show what was normal for you. Maybe you had flare-ups twice a year. Maybe you managed pain with over-the-counter medicine. Your post-accident records show the change: more frequent pain, new limitations, stronger medication.
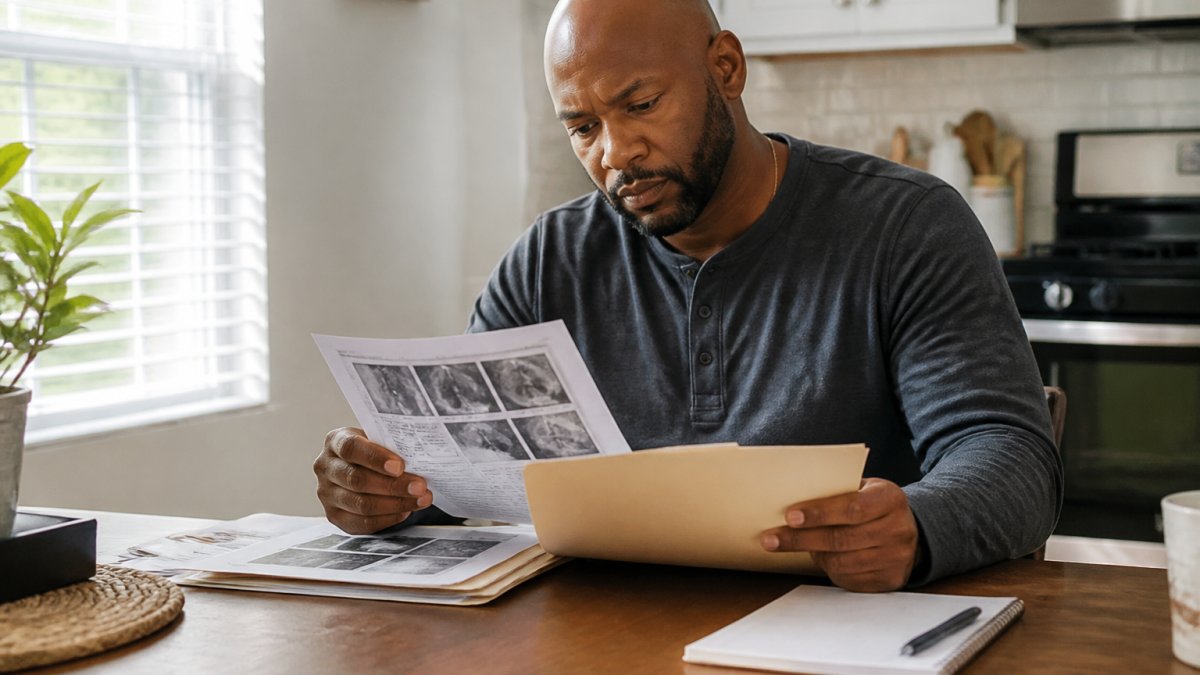
The contrast is the proof. A doctor can point to the records and say, “This patient’s condition was stable before, and it declined after the event.”
What to Do When Pre-Accident Records Are Missing
Many people have no pre-accident records at all. They managed their condition at home and never saw a doctor. That does not sink your claim.
- Use witness statements from people who knew your daily limits
- Point to work records showing you performed your job without restrictions
- Reference any pharmacy or over-the-counter purchases
- Rely on your own consistent account of your baseline
A gap in records is common. Insurers know this. What matters is building the strongest picture you can from what exists. (Source: Occupational Safety and Health Administration (OSHA) guidelines)
Step 4: Get a Doctor Statement for Your Injury Claim
A doctor statement for an injury claim is a written opinion that links your worsening condition to the accident. It is often the single most important document in an aggravation case.
The statement should cover four things:
- Your condition before the accident, based on records or history
- Your condition after the accident
- The change in symptoms and function
- The doctor’s opinion that the accident caused or worsened the condition
Ask your treating doctor to be specific. “Patient is worse” is weak. “Patient’s pain level rose from manageable to limiting daily activity, and this change followed the accident” is strong.
Schedule a Free Consultation →
Not every doctor will write this kind of statement. Some are not comfortable with legal opinions. If yours hesitates, an attorney can help explain what is needed.
Step 5: Establish Causation and Prepare for Insurer Review
Causation is the link between the accident and your worsened condition. It is the heart of any aggravation claim.
To prove causation, you need medical evidence that connects the event to the change. Your doctor’s opinion carries the most weight. Records, imaging, and a clear timeline support it.
Insurers will look for reasons to deny. They may argue your condition would have gotten worse anyway. They may point to gaps in treatment. They may ask you to attend an independent medical examination.
Natural Progression vs. Event-Related Worsening
This is the argument you must be ready for. Insurers often claim your condition simply got worse on its own, a process called natural progression.
Here is how to separate the two:
- Timing: Did the change happen right after the accident, or gradually over years?
- Mechanism: Did the accident cause trauma that explains the worsening?
- Pattern: Was your condition stable before, then suddenly worse?
- Doctor’s view: Does your treating doctor link the change to the event?
If your condition was steady for years and then dropped sharply after a crash, that pattern points to the accident, not natural progression.
How Aggravation Affects a Pre-Existing Condition Personal Injury Settlement
A pre-existing condition personal injury settlement can still be substantial. You are entitled to compensation for the worsening, even if the underlying condition was not the defendant’s fault.
The key is apportionment. This means separating the harm caused by the accident from the harm that existed before. You recover for the aggravation alone, not the original condition.
For example, if your prior back pain was mild and the accident made it severe, your damages reflect that jump in severity. This can include:
- Additional medical bills tied to the worsening
- Lost wages from new work restrictions
- Pain and suffering from the increased symptoms
- Future care for the aggravated condition
Proving the apportionment is where strong evidence and a clear doctor statement pay off. Insurers will try to attribute as much as possible to your prior condition to lower the offer.
According to the Cornell Legal Information Institute overview of tort law, a defendant is generally liable only for the harm they caused, which is why separating old from new matters so much.
Conclusion: Protect Your Claim With Prompt Action
Aggravation claims are winnable, but they demand fast, organized action. The longer you wait, the harder it becomes to show what your baseline was and how the accident changed it.
If you are dealing with a pre-existing condition made worse by an accident, do not face the insurer alone. At Merritt & Merritt Law Firm, we bring over 45 years of trial experience to every case. We offer 24-hour service, and we can meet you at your home, office, or hospital. You pay only if we win.
Schedule a free consultation with Merritt & Merritt Law Firm and get a clear, honest read on what your aggravation claim is worth.
Frequently Asked Questions
How do you prove an accident aggravated a pre-existing condition?
You prove aggravation by showing a measurable change in your symptoms or function after the event. This means comparing your baseline before the accident to your condition after it. Strong proof includes prior medical records documenting your baseline, imaging studies showing a change, and a doctor’s statement linking the worsening to the accident. An evidence timeline that organizes records by date helps insurers and courts see the connection clearly.
Can medical records prove aggravation of a pre-existing injury?
Medical records are the foundation of an aggravation claim, but they work best when they show a clear before-and-after picture. Records from before the accident establish your baseline, while records after the accident document increased pain, new functional limitations, or changes on imaging. If you had gaps in treatment before the accident, a doctor can still describe your prior condition based on your history and any available documentation.
Do I need a medical expert to prove aggravation of a pre-existing condition?
In most cases, yes. A treating physician or an independent medical expert can explain how the accident worsened your underlying condition rather than just describing symptoms. This doctor statement for your injury claim connects your medical history to the event and addresses causation. Without expert input, insurers often argue that your symptoms are simply natural progression of the prior condition.
How does aggravation of a pre-existing condition affect a personal injury settlement?
A pre-existing condition personal injury settlement typically covers only the worsening caused by the accident, not the original condition. Insurers may try to reduce your claim by arguing your symptoms would have progressed anyway. Strong medical evidence, a clear timeline, and expert testimony help separate accident-related worsening from natural progression, which supports a fairer settlement for the aggravated portion of your injury.
Our Locations
Atlanta/Decatur
1 West Court Square
Suite 750
Decatur, GA 30030
Savannah
100 Bull Street
Suite 200
Savannah, GA 31401
Statesboro
15 West Main Street
Statesboro, GA 30458
Houston
1415 Louisiana Street,
Suite 1800,
Houston, TX 77002
Jacksonville
841 Prudential Drive
12th Floor
Jacksonville, FL 32207

Contact Us
© Copyright 2026 Merritt & Merritt Law Firm. All rights reserved.