
call us 24/7 1-800-738-WE-WIN
call us 24/7 1-800-738-WE-WIN
Serving All of Georgia, Florida, & Texas
What Does Liability Cover If You Are Not at Fault?
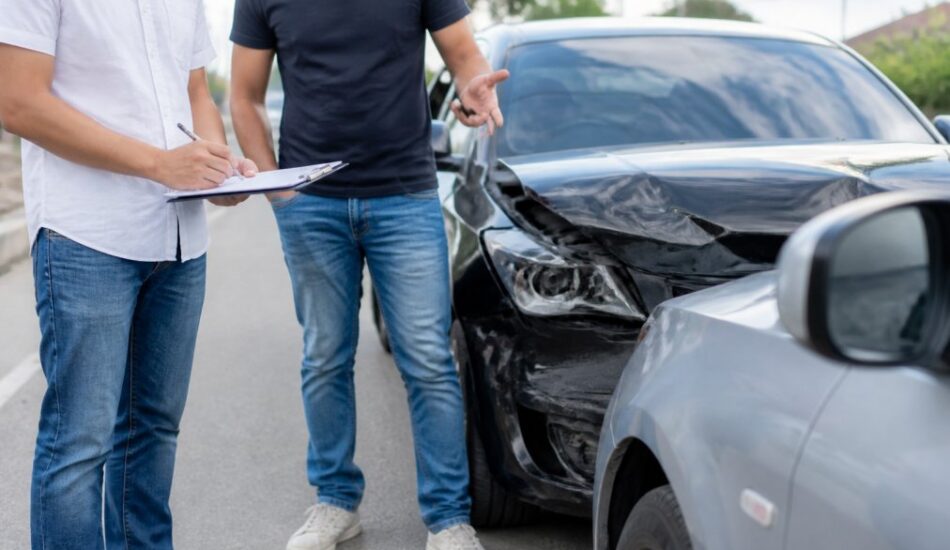
Table of Contents
- How Liability Coverage Works When Another Driver Causes the Crash
- What Liability Insurance Covers: Bodily Injury and Property Damage
- What Liability Coverage Does Not Pay For
- How to File a Third-Party Insurance Claim Against the At-Fault Driver
- What Is Subrogation in Car Insurance and How It Affects You
- At-Fault vs No-Fault Insurance States: Know Your Options
- Why Liability Limits May Leave a Coverage Gap
- Talk to an Attorney About Your Accident Claim
- Frequently Asked Questions
Last Updated: September 5, 2026
How Liability Coverage Works When Another Driver Causes the Crash
Liability coverage pays for damages you cause to others, so it generally does not pay for your own injuries or vehicle repairs when someone else is at fault. If another driver causes the crash, their liability coverage is the primary source of compensation for your medical bills and property damage.
Call the Merritt & Merritt Law Firm at 404-975-1775. Offices in Atlanta/Decatur, Savannah, Statesboro, and Houston.
You file a claim against the at-fault driver’s policy, not your own. Their bodily injury and property damage limits determine how much you can recover. When those limits are too low, or when the other driver has no insurance at all, the situation gets complicated quickly.
What Liability Insurance Covers: Bodily Injury and Property Damage
Liability coverage on the at-fault driver’s policy pays for two categories of harm: bodily injury and property damage. Bodily injury liability covers the medical expenses, lost wages, and pain and suffering of people injured by the policyholder. Property damage liability covers repairs to your vehicle and other damaged property, such as a fence or guardrail.
For the injured party, this is a third-party claim. The at-fault driver’s insurance adjuster investigates the accident, reviews the police report, and determines whether to accept liability and offer a settlement.
Bodily Injury Liability: Medical Expenses, Lost Wages, and Pain and Suffering
When the at-fault driver’s bodily injury coverage applies, it can reimburse medical expenses including ambulance transport, emergency room care, surgery, physical therapy, and future treatment. It also compensates for lost wages and pain and suffering.
The key limitation is the at-fault driver’s liability limits. If their policy only carries modest bodily injury coverage and your medical bills exceed that amount, the remaining balance falls on you unless you have uninsured or underinsured motorist coverage of your own.
Property Damage Liability: Vehicle Repairs and Rental Reimbursement
Property damage liability pays to repair or replace your vehicle when the at-fault driver is responsible. Many policies also include rental car reimbursement, which covers the cost of a rental vehicle while your car is in the shop. Not every policy includes this automatically, so it is worth asking the adjuster whether rental coverage is available under the at-fault driver’s policy.
What Liability Coverage Does Not Pay For
Liability coverage from the at-fault driver will not pay for everything you might expect. It does not cover your own medical expenses if you carry only liability insurance and the at-fault driver is uninsured. It also does not cover damage to your own vehicle when you are at fault, which is why collision coverage exists.
Additionally, liability coverage does not pay for legal defense if you are sued. That protection comes from your own policy’s liability coverage, which funds your attorney and any judgment against you up to your policy limits. When you are not at fault, your own liability coverage is not typically implicated, but the distinction matters if fault is disputed.
How to File a Third-Party Insurance Claim Against the At-Fault Driver
Filing a third-party insurance claim requires a systematic approach. The strategy you use can change dramatically depending on the state where the accident occurred, due to a legal principle called comparative negligence.
The Critical First Step: Understanding Your State’s Fault Rules
Before you pick up the phone, know how your state handles fault. Most states use comparative negligence, meaning your financial recovery can be reduced by your own percentage of fault (nolo.com). This can mean the difference between a full settlement and receiving nothing.
There are two main types of comparative negligence:
- Pure Comparative Negligence: States like Florida allow you to recover damages even if you are 99% at fault. Your settlement is simply reduced by your degree of fault. For example, if your damages are $10,000 and you are found 20% at fault, you can still recover $8,000.
- Modified Comparative Negligence: This is the most common system, used in states like Georgia and Texas. Under this rule, you are barred from recovering any damages if you are found to be 50% or more at fault. If you are 49% at fault, your recovery is reduced; if you are 50% at fault, you get nothing.
A few states, including Alabama and Virginia, follow the stricter contributory negligence rule, where any fault on your part, even 1%, completely bars you from recovering damages (law.cornell.edu).
Why this matters for your claim: The at-fault driver’s adjuster will immediately look for evidence that you contributed to the crash, speeding, distraction, or failure to yield. This is why the documentation you gather at the scene is so critical.
The Step-by-Step Process with a Legal Strategy
- Call the police and obtain an accident report. The officer’s narrative and fault determination, while not legally binding, carry significant weight with adjusters.
- Document the scene strategically. Take pictures of road conditions, traffic signs, skid marks, and vehicle positions. Get witness contact information and ask if they would give a statement, a witness who saw the other driver run a red light is your strongest weapon against a comparative fault claim.
- Seek medical attention immediately. Even if you feel fine, go to a doctor. In a comparative negligence state, a delay in treatment can be used to argue your injuries are not serious or were pre-existing. A prompt medical record creates a direct link between the crash and your injuries.
- Do not give a recorded statement without legal counsel. The other driver’s adjuster is trained to elicit admissions. You have the right to decline a recorded statement and provide a written statement instead.
- Preserve all evidence of damages. Keep every receipt: medical bills, prescription costs, car rental receipts, and proof of missed work. Your documentation is your counter-argument.
In modified comparative negligence states, the at-fault driver’s insurer may offer a quick settlement early on, hoping you will accept it before you fully understand the extent of your injuries or before they have completed their own fault analysis. If you accept a settlement, you sign away your right to pursue further compensation. Once you sign, you cannot go back and ask for more money if you discover your injuries are worse than initially diagnosed.
The Role of the Insurance Adjuster in a Fault Dispute
The adjuster’s job is to protect the insurance company’s bottom line. They will conduct their own investigation and use any evidence of your comparative fault to reduce the settlement offer. An attorney who can independently investigate and push back on the adjuster’s fault analysis is often the most effective way to protect your recovery.
What Is Subrogation in Car Insurance and How It Affects You
Subrogation is the legal process by which an insurance company recovers money it paid out from the party responsible for the loss. In a car accident context, your own insurer may pay your claim under collision or medical payments coverage, then pursue the at-fault driver’s insurer to recover those costs.
Subrogation matters because it can affect your deductible and premium. If your insurer successfully recovers from the at-fault driver, you may receive your deductible back. However, filing a claim on your own policy may lead your insurer to raise your premium even though you were not at fault.
At-Fault vs No-Fault Insurance States: Know Your Options
The distinction between at-fault and no-fault states changes how you pursue compensation. In a tort state, the at-fault driver’s liability coverage pays for your damages, and you may pursue a personal injury lawsuit. In a no-fault state, your own personal injury protection pays medical bills regardless of fault, but your ability to sue for pain and suffering is restricted unless your injuries meet a serious threshold.
Georgia and Florida both operate under different systems, so knowing which rules apply to your accident is essential. An attorney can identify whether your claim proceeds through a third-party claim against the at-fault driver or through your own personal injury protection first.
Why Liability Limits May Leave a Coverage Gap
State-mandated minimum liability coverage is often far too low to cover a serious accident. When the at-fault driver carries only minimum limits, your medical expenses and lost wages can quickly exhaust their policy, leaving a coverage gap you must fill.
The Reality of State Minimums
The minimum liability limits required by law are designed to provide a baseline of protection, not to cover a catastrophic accident. A common minimum requirement is 25/50/25, which means:
- $25,000 for bodily injury per person
- $50,000 for bodily injury per accident (total)
- $25,000 for property damage
However, many states have even lower minimums. For instance, Florida requires only $10,000 in property damage liability and does not require bodily injury liability for most drivers (flsenate.gov). Georgia’s minimum is 25/50/25 ($25,000 per person, $50,000 per accident, $25,000 property damage).
Consider this scenario: You are hit by a driver with minimum coverage in a state like Georgia. Your hospital stay alone costs $45,000, and your car is totaled with a replacement value of $20,000. The at-fault driver’s policy will only pay $25,000 toward your medical bills and $20,000 toward your car. You are now facing a $20,000 medical bill and no car payment gap.
How Underinsured Motorist (UIM) Coverage Steps In
This is precisely where your own Underinsured Motorist (UIM) coverage becomes critical, it steps in when the at-fault driver’s liability limits are insufficient.
Here is how the mechanics work:
- The at-fault driver’s policy pays first. Their insurer pays up to their policy limits.
- Your UIM coverage pays the difference. Your UIM policy will cover the remaining damages, up to your own UIM policy limits.
For example, if your damages are $100,000 and the at-fault driver has a $25,000 policy limit, your UIM coverage with a $100,000 limit would pay the remaining $75,000, up to your policy’s terms.
If you have multiple vehicles on your policy, some states allow you to “stack” your UIM coverage, meaning you can combine the limits from each vehicle. For example, if you have two cars with $50,000 in UIM coverage each, you might be able to access $100,000 in total UIM protection. However, stacking is prohibited in many states, and your insurer must clearly explain your options when you purchase the policy. Ask your agent whether stacking applies in your state.
The Uninsured Motorist (UM) Scenario
If the at-fault driver has no insurance at all, your Uninsured Motorist (UM) coverage acts as a stand-in for their liability policy. It covers your medical bills, lost wages, and in some states, pain and suffering, up to your UM policy limits. Without UM coverage, you would be forced to pursue the at-fault driver personally, which is often futile if they lack the assets to pay a judgment.
The Gap Between Policy Limits and Actual Damages
A common misconception is that the at-fault driver’s property damage liability will cover the full cost of your vehicle. If your car is totaled and you owe more on your loan than its actual cash value, their coverage only pays the depreciated value. The “gap” is your responsibility unless you carry Gap Insurance.
The Strategic Decision: When to Involve Your Own Insurer
When the at-fault driver’s limits are clearly insufficient, you have a decision to make. You can either:
- Accept the at-fault driver’s policy limits and then file a UIM claim with your own insurer.
- File a claim with your own insurer first under your collision coverage to get your car repaired quickly, and let your insurer pursue subrogation against the at-fault driver to recover their costs.
Filing a UIM claim is more complex than a standard third-party claim. Your own insurer is now paying you, so they will scrutinize the claim carefully, may require the at-fault driver’s policy limits in writing, and may dispute the claim’s value. Legal representation can be invaluable here, as your insurer’s interests are not always aligned with yours.
Talk to an Attorney About Your Accident Claim
Sorting out liability coverage, filing a third-party claim, and negotiating with an insurance adjuster is demanding work, especially while you are recovering from injuries. The attorneys at Merritt & Merritt Law Firm bring over 45 years of trial experience to car accident and personal injury cases, and they offer 24-hour service with the option to meet you at home, in the office, or in the hospital. You pay only if they win, which means there is no upfront cost to learn whether you have a viable claim.
Insurance companies often push injured victims toward quick, low settlements. Legal representation levels the playing field by investigating the claim, calculating the full value of your damages, and negotiating for a fair outcome.
Frequently Asked Questions
Does liability insurance pay for my repairs if I am not at fault?
No. Liability insurance pays for damage you cause to others, not your own vehicle. If the other driver is at fault, their liability coverage should pay for your repairs. You file a third-party claim against their policy. If they lack enough coverage or are uninsured, your own uninsured or underinsured motorist coverage may step in to fill the gap.
Will my insurance rates go up if I am not at fault?
Possibly, but it depends on your insurer and state rules. Some states prohibit rate increases after not-at-fault accidents. In other states, insurers may raise rates if they see you as a higher risk, even when the other driver caused the crash. Ask your agent about your specific policy and state regulations before assuming your rates will stay the same.
What happens if the at-fault driver has very low liability limits?
If the at-fault driver’s liability limits are too low to cover all your medical expenses and lost wages, you may face a coverage gap. Your underinsured motorist coverage can help pay the remaining costs up to your policy limits. An attorney can also investigate whether other sources of compensation exist, such as an umbrella policy or a claim against a commercial vehicle’s higher limits.
What does liability insurance not cover in an accident?
Liability insurance does not cover your own medical bills, your vehicle repairs, or rental car costs. It only pays for injuries and property damage you cause to others. When you are not at fault, the other driver’s liability coverage is the primary source for your losses. Your own collision coverage or medical payments coverage may also apply depending on your policy.
Understanding what liability cover does when you are not at fault is the first step toward protecting your financial recovery. The process involves filing a third-party claim, navigating subrogation, and knowing whether your state follows at-fault or no-fault rules. Schedule a free consultation with Merritt & Merritt Law Firm to have your case evaluated immediately and get clear, realistic expectations about your path forward.
Our Locations
Atlanta/Decatur
1 West Court Square
Suite 750
Decatur, GA 30030
Savannah
100 Bull Street
Suite 200
Savannah, GA 31401
Statesboro
15 West Main Street
Statesboro, GA 30458
Houston
1415 Louisiana Street,
Suite 1800,
Houston, TX 77002
Jacksonville
841 Prudential Drive
12th Floor
Jacksonville, FL 32207

Contact Us
© Copyright 2026 Merritt & Merritt Law Firm. All rights reserved.