
call us 24/7 1-800-738-WE-WIN
call us 24/7 1-800-738-WE-WIN
Serving All of Georgia, Florida, & Texas
Personal Injury vs Property Damage Claims: Key Differences
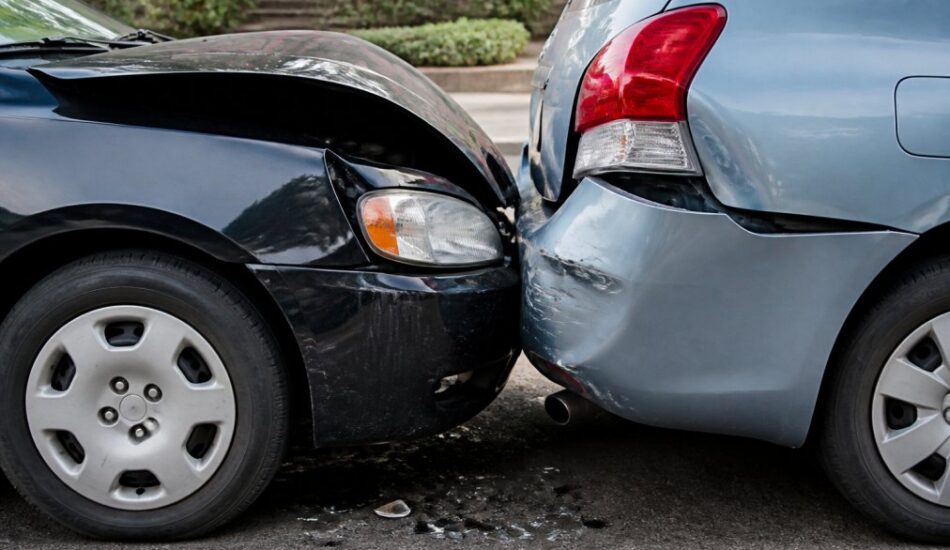
Table of Contents
- Personal Injury vs Property Damage: What Is the Difference?
- Side-by-Side Comparison of Injury and Property Claims
- Compensation for Injuries vs Compensation for Property
- Why Fault and Insurance Coverage Treat Each Claim Differently
- How to Calculate Pain and Suffering Damages
- Statute of Limitations for Car Accidents in Georgia
- Do I Need a Lawyer for a Property Damage Claim?
- Get Clear Answers About Your Claim
- Frequently Asked Questions
Last Updated: September 8, 2026
Personal Injury vs Property Damage: What Is the Difference?
The difference between personal injury and property damage claims comes down to what was harmed: your body or your belongings. A personal injury claim seeks compensation for physical harm, medical expenses, and related losses, while a property damage claim covers repairs or replacement of damaged items like your vehicle. At Merritt & Merritt Law Firm, we guide injury victims through both types of claims, and we often see clients confuse the two when an insurance adjuster calls.
Understanding this distinction matters because it shapes how much you can recover and how the claim process unfolds. Bodily injury and property damage are handled separately, even when they result from the same accident. Most people realize this only after they have accepted a quick offer for their car, only to discover their medical bills remain unpaid.
Below, we will show you exactly how these claims differ, what compensation is available for each, and why fault and insurance coverage treat them so differently. The key insight most guides miss: the insurance company wants to close your property damage claim quickly because it is cheaper, while your injury claim requires careful documentation to reach its full value.
Side-by-Side Comparison of Injury and Property Claims
A single car accident can generate two entirely separate claims, each governed by its own rules and handled by different adjusters. The property damage claim addresses vehicle repair and other damaged personal property, while the personal injury claim addresses your medical expenses, lost wages, and pain and suffering.
| Claim Type | Covers | Insurance Coverage | Key Documentation |
|---|---|---|---|
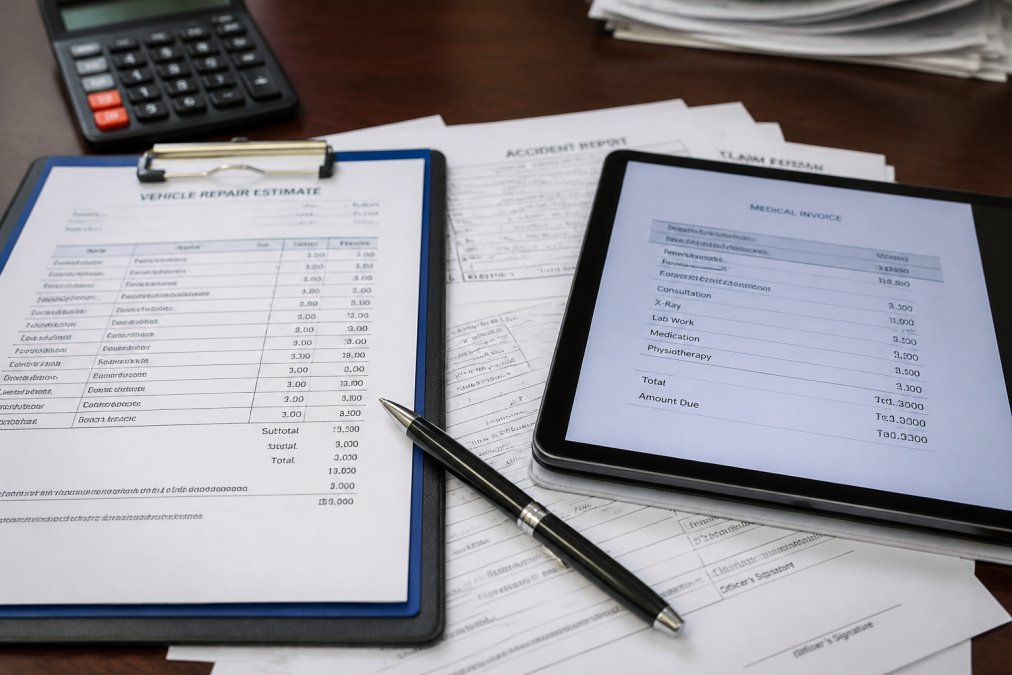
| Property Damage | Vehicle repair, rental car, personal property | Property damage liability | Repair estimates, photos, accident report |
| Personal Injury | Medical bills, lost wages, pain and suffering | Bodily injury liability | Medical records, treatment notes, bills |
The insurance adjuster handling your vehicle repair is often a different person from the one evaluating your injury claim. That adjuster’s job is to minimize what the insurer pays out, and the two claims are valued on completely different timelines. Your car might be repaired within weeks, but your injury claim may not settle until you reach maximum medical improvement.
Compensation for Injuries vs Compensation for Property
Compensation for property damage is relatively straightforward: the insurer owes you the cost to repair your vehicle or its actual cash value if the car is totaled. You may also recover rental car costs and reimbursement for personal property destroyed in the crash, such as a laptop or phone. These are considered economic damages with clear, documented values.
Compensation for injuries is far more complex. Injury claims involve both economic and non-economic damages, and valuing them requires medical evidence and legal judgment. This is why the difference between personal injury and property damage claims matters so much when you are negotiating with an insurer.
Economic and Non-Economic Damages in Injury Claims
Economic damages include medical expenses, lost wages, and out-of-pocket costs like mileage to appointments or prescription medications. These have paper trails and are relatively easy to calculate. Non-economic damages cover pain and suffering, emotional distress, and loss of enjoyment of life, which have no receipt and require careful documentation (peer-reviewed research).
Vehicle Repair, Diminished Value, and Out-of-Pocket Costs
Property damage claims can include diminished value, which is the reduction in your vehicle’s resale value simply because it has been in an accident, even after perfect repairs (ncua.gov). Many adjusters will not mention this unless you ask. Out-of-pocket costs like your insurance deductible and towing fees are also recoverable, but you must submit documentation for each expense.
Accepting a property damage settlement does not automatically waive your right to pursue an injury claim, but signing a broad release can. Read every release form carefully before signing, and never let an adjuster convince you that a quick check for your car means your injury claim is also closed.
Why Fault and Insurance Coverage Treat Each Claim Differently
Fault determination affects each claim independently, and the insurance coverage available for each is purchased separately under your policy. Bodily injury liability coverage pays for the other party’s injuries when you are at fault, while property damage liability coverage pays for their vehicle repairs (iii.org). These are distinct coverage types with separate policy limits.
When you file a claim against another driver, their bodily injury liability limit applies to your injury claim, while their property damage liability limit applies to your vehicle repairs. If the at-fault driver has low limits, your injury claim may exceed what their policy will pay, which is where your own uninsured or underinsured motorist coverage becomes critical.
The insurance adjuster investigates fault separately for each claim. An accident report may assign fault clearly, but insurers conduct their own investigation, reviewing police reports, photos, and witness statements. This is why your documentation matters: the stronger your evidence of negligence, the harder it is for the insurer to shift blame.
How to Calculate Pain and Suffering Damages
Pain and suffering damages are calculated using one of two common methods: the multiplier method or the per diem method. The multiplier method takes your total economic damages, such as medical bills and lost wages, and multiplies them by a number between 1.5 and 5, depending on the severity of your injuries and how they affect your daily life.
The per diem method assigns a daily dollar amount for each day you suffer from the injury, from the accident date until you reach maximum recovery. While these formulas provide a starting point, insurance adjusters apply their own judgment, which is why two people with similar injuries can receive very different offers.
Schedule a Free Consultation →
What most guides miss is that documentation drives the multiplier. Consistent treatment records, a journal of your daily pain levels, and evidence of how the injury disrupted your work and family life all justify a higher multiplier. Sparse medical records give the adjuster an excuse to apply a lower one.
Keep a daily symptom journal from the day of the accident. Note your pain level each morning and night, activities you cannot perform, and how the injury affects your sleep and mood. This creates a contemporaneous record that strengthens your pain and suffering claim during settlement negotiations.
Statute of Limitations for Car Accidents in Georgia
The statute of limitations for car accidents in Georgia is generally two years from the date of the accident for personal injury claims. Property damage claims also carry a deadline under Georgia law. Missing these deadlines typically bars you from recovering anything at all, regardless of how strong your case is.
The clock starts running on the accident date, not when you finish treatment or when the insurance company makes its final offer. Many injured victims wait too long because they are focused on recovery, only to discover their claim has expired. If you were involved in an accident outside Georgia, the applicable deadline may differ, so confirm the rule for the state where the crash occurred.
Do I Need a Lawyer for a Property Damage Claim?
You may not need a lawyer for a straightforward property damage claim where the at-fault driver has clear coverage and accepts responsibility. If the insurer offers a fair repair estimate and your car is drivable, you can often handle the property damage portion yourself while focusing your energy on your injury claim.
You should consider legal representation when the property damage claim is contested, when the at-fault driver is uninsured, or when your vehicle is totaled and the insurer’s valuation seems low. An attorney also becomes valuable when your injury claim is substantial, because the property damage settlement can affect your overall recovery strategy.
The real risk is handling both claims alone and signing away your rights before understanding the full value of your injuries. Many accident victims accept an early settlement for their vehicle, not realizing the release they signed also limits their injury recovery.
Get Clear Answers About Your Claim
The difference between personal injury and property damage claims shapes every decision you make after an accident, from what documentation to gather to how you respond to an insurance adjuster. Property damage claims are about restoring your vehicle and belongings, while personal injury claims address your medical expenses, lost wages, and pain and suffering. Each follows its own timeline, coverage limits, and negotiation process.
At Merritt & Merritt Law Firm, our trial team has over 45 years of experience representing injury victims in Georgia and nationwide. We offer 24-hour service and attorneys who can visit you at home, in the office, or in the hospital, so you receive support even while recovering. You pay only if we win, and we provide clear, realistic expectations about your claim from the first consultation.
Schedule a free consultation to discuss your accident and learn what your claim may be worth.
Frequently Asked Questions
Can I file a personal injury claim and a property damage claim at the same time?
Yes. A car accident typically produces two separate claims: one for your injuries and one for your vehicle. They are handled independently, often by different adjusters and different coverage limits under the at-fault driver’s policy. Your injury claim covers medical expenses, lost wages, and pain and suffering. Your property damage claim covers vehicle repair or replacement and related out-of-pocket costs. You can pursue both simultaneously, and an attorney can manage both tracks to make sure one settlement does not undermine the other.
What is the statute of limitations for personal injury versus property damage in Georgia?
Georgia law sets a two-year statute of limitations for personal injury claims, which covers bodily injury, pain and suffering, and related damages. Property damage claims in Georgia also have a statute of limitations. These deadlines are strict. If you miss the filing window, you lose your right to recover. Because the clock starts on the accident date, prompt action protects your case. An attorney can confirm which deadline applies to each part of your claim and ensure the necessary paperwork is filed on time.
How does fault affect personal injury and property damage settlements?
Fault determines how much you can recover in both claim types. Georgia follows a modified comparative negligence rule. Your compensation is reduced by your percentage of fault. If you are found 50 percent or more at fault, you recover nothing. The same fault percentage applies to both your injury claim and your property damage claim, but each is calculated separately. The insurance adjuster investigates the accident report, photos, and witness statements to assign fault. Strong documentation of the other driver’s negligence supports a higher settlement on both claims.
Are pain and suffering damages calculated differently from vehicle repair costs?
Yes, and this is a common point of confusion. Vehicle repair costs are economic damages with a clear dollar value based on the repair estimate or the car’s fair market value. Pain and suffering is a non-economic damage with no receipt or invoice. Attorneys often calculate it using a multiplier method, where your total medical expenses are multiplied by a number from 1.5 to 5 based on injury severity, or a per-diem method based on a daily rate. Your medical records and treatment timeline are the evidence that supports the calculation.
Our Locations
Atlanta/Decatur
1 West Court Square
Suite 750
Decatur, GA 30030
Savannah
100 Bull Street
Suite 200
Savannah, GA 31401
Statesboro
15 West Main Street
Statesboro, GA 30458
Houston
1415 Louisiana Street,
Suite 1800,
Houston, TX 77002
Jacksonville
841 Prudential Drive
12th Floor
Jacksonville, FL 32207

Contact Us
© Copyright 2026 Merritt & Merritt Law Firm. All rights reserved.